Cross-border QR payments shift from connectivity to economic value
In the first eight months of 2026, cashless payment transactions rose 34.56 per cent in volume and 13.26 per cent in value year-on-year.
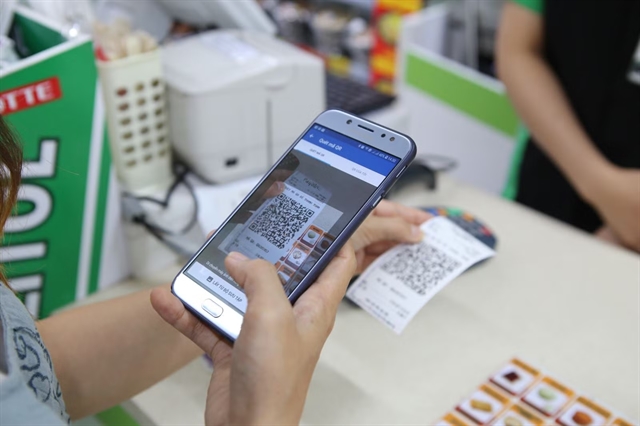
HÀ NỘI — Cross-border QR payments in Việt Nam are moving into a new phase, with policymakers and payment infrastructure operators focusing increasingly on how existing connections can be used more effectively to support tourism, retail and cross-border trade.
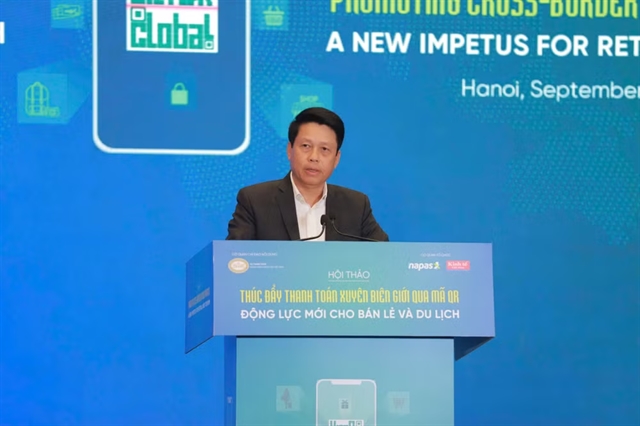
At the workshop "Promoting Cross-Border QR Payments: New Drivers for Retail and Tourism" held on September 25, the State Bank of Việt Nam (SBV) Deputy Governor Phạm Tiến Dũng said infrastructure connectivity should be viewed as the starting point rather than the ultimate objective.
"Infrastructure connectivity is the starting point, while economic connectivity is the goal to strive for," Dũng said.
The shift comes as cashless payments have expanded rapidly in Việt Nam.
By the end of 2025, nearly 89 per cent of people aged 15 and above had transaction accounts at banks or other permitted institutions, while the value of cashless payments was more than 28 times gross domestic product.
Between 2021 and 2025, the average annual growth rates in the number and value of cashless payment transactions were 58.86 per cent and 24.36 per cent, respectively.
The trend continued in the first eight months of 2026. According to the SBV, cashless payment transactions rose 34.56 per cent in volume and 13.26 per cent in value year-on-year.
QR payments alone reached 311 million transactions worth VNĐ274.2 trillion (US$10.6 billion), up 6.66 per cent in volume and 25.85 per cent in value.
Building on this domestic foundation, the SBV has promoted bilateral retail payment cooperation through QR codes with Thailand, Laos, Cambodia, China, South Korea and Singapore, while continuing to expand connectivity with other markets.
The expansion is already generating stronger transaction flows.
In the first eight months of 2026, transactions by visitors from Thailand, Laos and Cambodia in Việt Nam increased eightfold in volume and sixfold in value year-on-year.
Vietnamese users making transactions in the three markets recorded fivefold growth in volume and fourfold growth in value.
China has also emerged as a significant market for VietQRGlobal.
NAPAS connected with UPI in December 2025, Alipay in April 2026 and Weixin Pay in August.
By August, only four months after the expansion began, transactions by Chinese visitors using Chinese payment applications to scan VietQRGlobal in Việt Nam had tripled in volume and quadrupled in value compared with April.
NAPAS has separately expanded QR payment connectivity with Singapore and South Korea during 2026.
These developments are shifting the focus from whether payment systems can be connected to whether those connections are being used widely and efficiently.
Dũng said success should not be measured solely by the number of connected markets but also by actual usage, the coverage of payment acceptance points, service quality, costs, convenience and the value generated for consumers and businesses.
At the same time, broader connectivity creates greater requirements for security and risk management because cross-border payments involve banks, payment switches, intermediaries, technology platforms and different legal frameworks.
Dũng stressed that connectivity must be accompanied by quality and safety, particularly cybersecurity, fraud prevention, anti-money-laundering measures, data protection, customer rights and uninterrupted payment and settlement operations.
Domestic experience illustrates the importance of these safeguards.
Since the launch of the SIMO system on August 26, more than 5.1 million customer warnings had been issued, while nearly 1.7 million customers had suspended or cancelled transactions after receiving warnings, involving more than VNĐ5.7 trillion in transaction value.
"Safety and trust must be a consistent condition. Technology can change rapidly, but the principles of protecting users, clearly defining responsibilities, controlling risks and maintaining the resilience of the system must always remain at the centre," Dũng said.
Dũng also added that cross-border payments were not the responsibility of the banking sector alone.
"Cross-border payments are not a task solely for the banking sector," he said, calling for participation from banks, payment organisations, technology companies, tourism businesses, retailers and household businesses.
The next stage of VietQRGlobal will therefore involve not only adding new international connections but also increasing actual transactions, expanding acceptance networks and improving payment experiences for international customers.
Dũng said Việt Nam needs to turn its advantages in digital payment infrastructure and widespread adoption into concrete value for people, businesses and the economy. — BIZHUB/VNS