Bank credit surge supports high GDP growth target: SBV
As of the end of August 2026, credit proportion to agriculture, forestry, and fisheries accounted for 6.08 per cent; industry and construction accounted for 23.1 per cent; and trade and services accounted for 70.11 per cent.
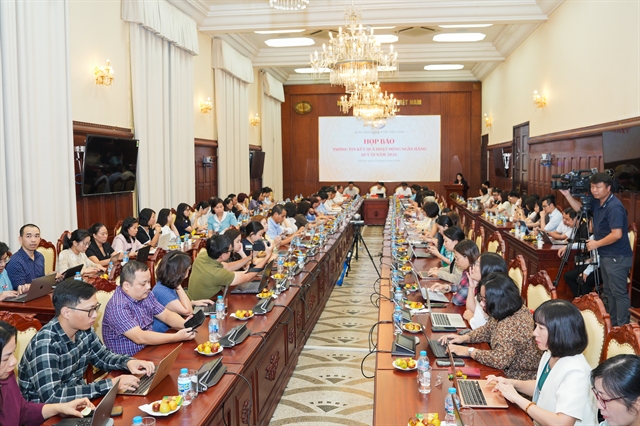
HÀ NỘI — Total outstanding loans across the banking system hit nearly VNĐ20.75 quadrillion (US$786 billion) as of September 30 this year significantly supporting Việt Nam’s high GDP growth target, Deputy Governor of the State Bank of Vietnam (SBV) Phạm Thanh Hà said at a press conference yesterday.
Speaking at the event to reveal the banking sector's performance in the first nine months of 2026 and outline steps for the remaining months of the year, Hà said that the credit increased by 11.59 per cent compared to the end of 2025 and 16.69 per cent year-on-year.
The results, he said, were due to effective measures taken by the SBV and commercial banks amid the difficulties in the global market.
“The SBV has implemented appropriate measures to help control inflation, stabilise the macro-economy, and support economic growth," Hà said.
"Notably, it has promptly directed credit institutions to implement credit solutions for specific sectors and industries, thereby facilitating access to credit for businesses and the public, especially large-scale and key projects.”
Nguyễn Xuân Bắc, deputy director of the SBV’s Credit Department, reported that bank credit structure in the first three quarters aligned with the economic sector structure.
“Credit capital continued to be channeled into production, business, and priority sectors," Bắc said.
"As of the end of August 2026, credit proportion to agriculture, forestry, and fisheries accounted for 6.08 per cent; industry and construction accounted for 23.1 per cent; and trade and services accounted for 70.11 per cent.”
“Priority sectors designated by the Government and the Prime Minister accounted for a significant share, such as agriculture and rural development at approximately 22 per cent; or sectors that gained high growth rates, such as exports with 33.32 per cent and high-tech enterprises with 39.62 per cent,” Bắc added.
Regarding interest rates, Hà said that the SBV continued to maintain benchmark interest rates, creating favourable conditions for credit institutions to access capital from the SBV at low costs, enabling them to support the economy.
The average interest rate for new deposits as of September 20 this year stood at 6.38 per cent per annum, an increase of 1.15 percentage points compared to the end of 2025.
Despite the rise, Hà noted that, the rising pace is slowing, and interest rate levels are essentially stabilising around a new baseline.
According to Phạm Chí Quang, director of the SBV’s Monetary Department, although the exchange rate and foreign exchange market have been under pressure from recent unpredictable global developments, the SBV managed the exchange rate flexibly, helping to absorb external shocks.
Effective coordination between monetary policy tools helped stabilise the foreign exchange market, contributing to macro-economic stability and inflation control. As a result, the foreign exchange market is operating smoothly, the legitimate foreign currency needs of the economy are being fully and promptly met, and the USD-VNĐ exchange rate is fluctuating flexibly, in accordance with market conditions, Quang said.
In the remaining months of the year, Hà said that the SBV will continue to flexibly manage monetary policy, closely coordinating with fiscal policy and other macro-economic measures to control inflation, contribute to macro-economic stability and support sustainable economic growth.
Interest rates will be managed in line with market developments, macro-economic conditions, inflation and monetary policy objectives. The central bank will also continue to closely monitor developments in deposit and lending interest rates for the market and for each credit institution.
"The SBV will continue to closely monitor international and domestic market developments," Hà added.
"It will manage exchange rates flexibly, in accordance with market conditions, and coordinate with other monetary policy tools to stabilise the foreign exchange market, contributing to macro-economic stability, controlling inflation and supporting economic growth." — VNS/BIZHUB