Việt Nam faces growing challenge of financing longer retirements
Việt Nam’s rapidly ageing population is forcing households to rethink how they prepare financially for retirement, as people live longer and healthcare costs and inflation rise, experts said.
HCM CITY — Việt Nam’s rapidly ageing population is forcing households to rethink how they prepare financially for retirement, as people live longer and healthcare costs and inflation rise, experts said.
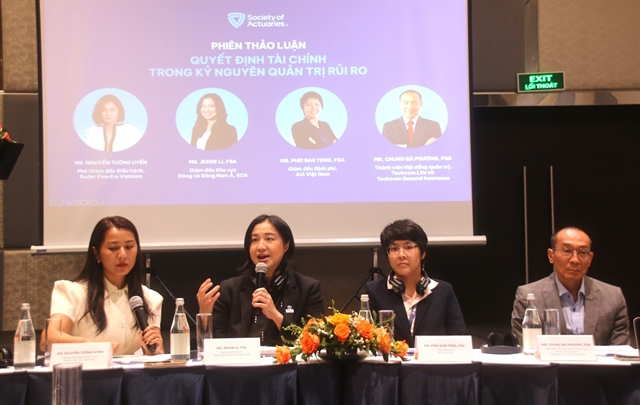
The experts were speaking at a meeting on financial decision-making and risk management organised by Society of Actuaries (SOA) in HCM City on Monday.
Nearly one in five people in the country is expected to be aged 60 or older by 2036, according to the SOA.
The organisation’s retirement research found that 71 per cent of Vietnamese respondents believed they had enough savings for retirement, while savings adequacy, inflation, healthcare costs and financial literacy remained among key concerns.
Savings and investments, pensions and family support are important sources of retirement income, while continued employment and insurance also play a role, the research found.
Ageing challenge
Longer life expectancy is changing the traditional calculation of how much people need to save for retirement.
A person retiring at 40, for example, could potentially need to finance another four decades of life. Even those retiring at a more conventional age may need to cover a substantially longer period than previous generations.
Jessie Li, a Fellow of the Society of Actuaries (FSA), regional director for East and Southeast Asia at the SOA, said early retirement meant taking responsibility for one’s income, time and health for decades after leaving a conventional job.
Healthcare needs generally increase with age, while inflation can erode the purchasing power of savings accumulated many years earlier, she said.
Li said people should begin allocating income to different financial goals as soon as they start earning, making saving a regular part of their financial plans.
The SOA research found relatively high confidence among Vietnamese workers and retirees about their retirement income, but noted that such confidence was self-reported and did not necessarily demonstrate that households had objectively adequate resources.
Rethinking retirement
The prospect of a decades-long retirement is also changing the way some people view retirement itself.
Chung Bá Phương, FSA, a board member of Techcom Life and Techcom General Insurance, said he had wanted to retire early since his 20s.
While retirement was once often associated with leaving the workforce completely, younger people may instead want to leave conventional employment and pursue work they find more interesting or meaningful, he said.
“If you just stay at home, look at the trees and eat three pieces of bread a day for 40 years, the financial calculation is quite simple. But if you want to do interesting work, that becomes a different calculation,” he said.
For people seeking early retirement, the most important asset may therefore not be money, land or gold, but their ability to continue creating value and generating income, Phương said.
Under this approach, retirement at 30, 40 or 50 does not necessarily mean withdrawing from economic activity. It can mean having greater freedom to choose what work to accept.
Planning for a changing future
Phei San Teng, FSA, chief actuary at AIA Vietnam, said financial plans need to evolve as people’s circumstances change.
For a single person, planning may include housing, food, travel and other living expenses, as well as supporting ageing parents. After marriage, the financial equation can expand to include childcare, education and potential support for children, she said.
Việt Nam’s declining birth rate makes the issue more significant because people may no longer be able to assume that children or younger generations will provide financial support in old age, Teng said.
“Therefore, we should not assume that we will always have children or future generations to provide financial support when we are old,” she said.
The demographic shift also creates challenges for insurers and other financial institutions whose products and liabilities can extend for decades.
Actuarial analysis can help institutions assess how products and financial commitments would perform under different assumptions about longevity, healthcare costs, inflation and investment returns.
For individuals, the same principle applies: a retirement plan based on a single estimate of future spending may be less resilient than one that considers a range of possible outcomes.
The SOA research found strong interest among Vietnamese respondents in guaranteed lifetime income and health-related protection, reflecting concerns over the risks associated with longer lives.
Việt Nam’s ageing transition therefore presents a challenge that goes beyond simply encouraging people to save more.
As people live longer, retirement planning increasingly involves questions about how long savings will need to last, how healthcare needs may change, whether people can continue generating income and how financial plans can adapt as family circumstances evolve.
For a country moving rapidly towards an ageing society, preparing for retirement is becoming less about reaching a single financial target and more about managing uncertainty over a potentially much longer later life. — VNS