SBV urges banks to proactively seek SME borrowers
SME credit outstanding rose 12.4 per cent from the start of 2026, faster than overall credit growth, but access to finance remains constrained by issues including collateral, financial transparency, management capacity and the ability to demonstrate cash flows.
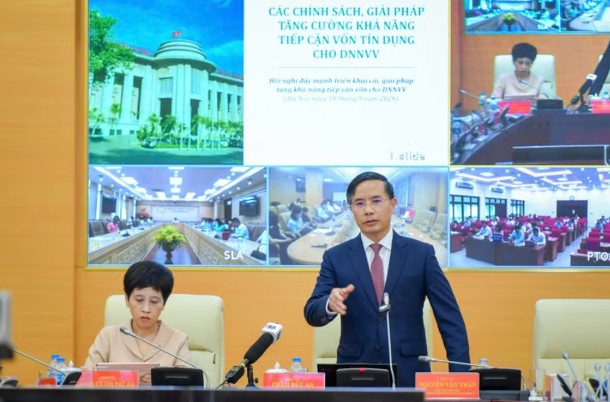
HÀ NỘI — Banks should proactively seek out small and medium-sized enterprises (SMEs) and assess borrowers more heavily on cash flows, business plans and data rather than relying mainly on collateral, while maintaining credit standards, Governor of the State Bank of Vietnam (SBV) Phạm Đức Ấn said on Friday.
"Banks need to move strongly from the mindset of businesses seeking banks to banks proactively seeking businesses," Ấn said at a conference on improving SME access to credit.
SME credit outstanding rose 12.4 per cent from the start of 2026, faster than overall credit growth, but access to finance remains constrained by issues including collateral, financial transparency, management capacity and the ability to demonstrate cash flows, the SBV said.
Ấn called on credit institutions to identify businesses' financing needs, work alongside them, improve lending procedures and shorten approval times while complying with regulations. Expanding credit does not mean lowering lending standards, he said.
Banks should study credit assessment methods that place greater weight on production and business plans, cash flows, credit histories, management capacity and corporate data, he said.
Linking tax, e-invoice, land, business registration and social insurance data with the credit information system could help shorten appraisal times and provide lenders with a broader basis for assessing borrowers.
Đỗ Văn Vẻ, chairman of the Hưng Yên Province Business Association, said banks should to make greater use of technology and data, including cash flows, contracts, orders, payment histories, tax records and e-invoices, to assess the overall capacity of borrowers.
Đào Minh Tú, deputy chairman of the Vietnam Banks Association, said that a shared SME data centre should be developed on a national-wide scale to facilitate data-based lending.
Experts also called for stronger risk-sharing mechanisms among the State, banks and businesses, as well as more effective use of credit guarantee funds and the SME Development Fund.
Such mechanisms could help banks expand lending to businesses with limited collateral while maintaining safety standards, provided that credit assessment is improved and corporate transparency strengthened.
Businesses themselves must improve governance, financial transparency and cash-flow management, fulfil their obligations and prepare viable business plans.
SMEs account for about 98 per cent of active businesses Việt Nam.
The SBV's statistics showed that more than 100 credit institutions had outstanding loans to SMEs as of August 28, with total credit worth more than VNĐ4.1 quadrillion (US$155 billion), up 12.4 per cent from the end of 2025 and accounting for about 20 per cent of total credit in the economy.
Total credit to the economy reached nearly VNĐ20.5 quadrillion, up 10.24 per cent.
The SBV is also seeking to expand preferential lending programmes for SMEs and sectors identified as growth drivers.
After more than a month of implementation, the number of commercial banks announcing preferential credit programmes increased to 19 from 4, with their combined lending scale exceeding VNĐ407 trillion.
Interest rates under the programmes were 1-2 percentage points a year lower than banks' average lending rates for loans of comparable maturities.
The programmes target areas including agriculture and rural development, supporting industries, high technology, exports, the digital economy, artificial intelligence, semiconductor manufacturing, processing and manufacturing, and green projects. — VNS