Market expected to recover this week: experts
After the sharp run of losses, the VN-Index could stage a technical rebound, at least early this week, with the nearest resistance zone at 1,715–1,750 points.
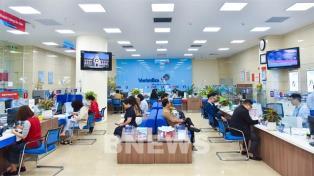
Clients conduct transactions at the headquarters of Bảo Việt Securities Company. — VNA/VNS Photo
HÀ NỘI — The stock market recorded its fourth consecutive weekly decline, with the VN-Index losing 29.18 points to close at 1,705.91 points, bringing its cumulative loss over the four weeks to nearly 110 points as liquidity weakened and investors remained cautious.
On the Hochiminh Stock Exchange (HoSE), average matched trading volume fell 16.5 per cent week-on-week to 583.6 million shares per session.
Investor sentiment remained subdued, with trading generally lacklustre. Some small-cap and highly speculative stocks nevertheless rallied as risk-tolerant investors sought short-term opportunities.
The market's headline performance has also masked a widening divergence among listed stocks. Since the beginning of 2025, gains in the VN-Index have been supported mainly by a handful of large-cap shares, particularly those linked to the Vingroup ecosystem.
Excluding these stocks, the broader market has declined by around 7 per cent. Overall market earnings growth has also slowed from 40 per cent to 12 per cent, falling to 4.6 per cent when Vingroup's impact is excluded.
Concentrated capital flows have pushed the valuations of some leading companies to around 10 times book value.
Meanwhile, many businesses with sound underlying fundamentals and expected revenue growth have seen their share prices move sideways or fall, weighing on the performance of short-term investment portfolios.
In its latest report, Dragon Capital highlighted the gap between the benchmark and the broader market. Excluding influential stocks such as Vingroup (VIC), Vinhomes (VHM) and Vinpearl (VPL), the VN-Index would have fallen 9.4 per cent since the beginning of the year, while its price-to-earnings (P/E) ratio would stand at just 11.4 times.
That valuation is below the level recorded during the tariff-related market volatility in April 2025 and approaches troughs seen in 2020 and 2022, the report said.
However, low valuations alone may not be enough to draw investors back.
A stock trading below its historical average may still struggle to attract capital if its expected return is insufficient compared with alternative investments.
Market experts said a recovery would not necessarily require all macroeconomic conditions to improve first. Buying interest could return once share prices have fallen sufficiently to offer attractive expected returns.
Liquidity and market interest rates have shown signs of stabilising following support measures by the State Bank of Vietnam, but borrowing costs have yet to show clear signs of peaking.
To identify a potential market reversal, investors should monitor four indicators: improving liquidity, broader market participation, a decline in the number of stocks hitting new lows, and the emergence of leading sectors.
Nguyễn Tấn Phong, an analyst at Pinetree Securities, said the market's late-session recovery on Friday was a positive signal, noting that capital had begun returning to banking, real estate and securities stocks, which have a significant influence on overall market sentiment.
After the sharp run of losses, the VN-Index could stage a technical rebound, at least early this week, he said. The nearest resistance zone is 1,715–1,750 points, corresponding to a former support area that the index recently breached.
With October 20 the deadline for companies to release third-quarter financial statements, the market is expected to remain highly selective. Capital is likely to favour stocks with strong business results rather than lifting the market broadly.
"However, this is only a rebound, and there is not yet sufficient evidence to confirm that the market has formed a bottom," the Pinetree analyst cautioned.
Phong identified domestic lending rates as the market's biggest risk. Further hawkish signals from the US Federal Reserve could add pressure on the Vietnamese đồng and prolong foreign net selling, while elevated energy prices could limit the State Bank's room to ease monetary policy.
If a rebound is not accompanied by stronger capital inflows, the VN-Index could retest the 1,700-point level.
This week, ASEAN Securities identified 1,680–1,700 points as the VN-Index's nearest support zone and 1,715–1,735 points as its first resistance area.
The performance of banking, securities and real estate stocks will be important in determining whether the market can establish a bottoming zone. — BIZHUB/VNS